• Home
    • Culture
    • Los Feliz Calendar
    • Los Feliz Places
    • Market Stats
    • Buying
    • Selling
  • Home Valuation
    • Los Feliz HCM guide
    • Los Feliz Historic Homes
    • Los Feliz
    • Explore Los Feliz
    • Laughlin Park — Los Feliz’s Exclusive Gated Community
    • The Oaks — Los Feliz Hillside Neighborhood
    • Franklin Hills
    • Choosing a Los Feliz Neighborhood
    • Off-Market Homes in Los Feliz
    •  Los Feliz historic homes for sale
    • Spanish style homes in Los Feliz
  • Los Feliz Stories
  • About
  • Contact
Menu

Los Feliz Living & Real Estate

  • Home
  • Culture
    • Culture
    • Los Feliz Calendar
    • Los Feliz Places
  • Market
    • Market Stats
    • Buying
    • Selling
  • Home Valuation
  • HCM+Historic
    • Los Feliz HCM guide
    • Los Feliz Historic Homes
  • Los Feliz Locations
    • Los Feliz
    • Explore Los Feliz
    • Laughlin Park — Los Feliz’s Exclusive Gated Community
    • The Oaks — Los Feliz Hillside Neighborhood
    • Franklin Hills
    • Choosing a Los Feliz Neighborhood
    • Off-Market Homes in Los Feliz
    •  Los Feliz historic homes for sale
    • Spanish style homes in Los Feliz
  • Los Feliz Stories
  • About
  • Contact
×
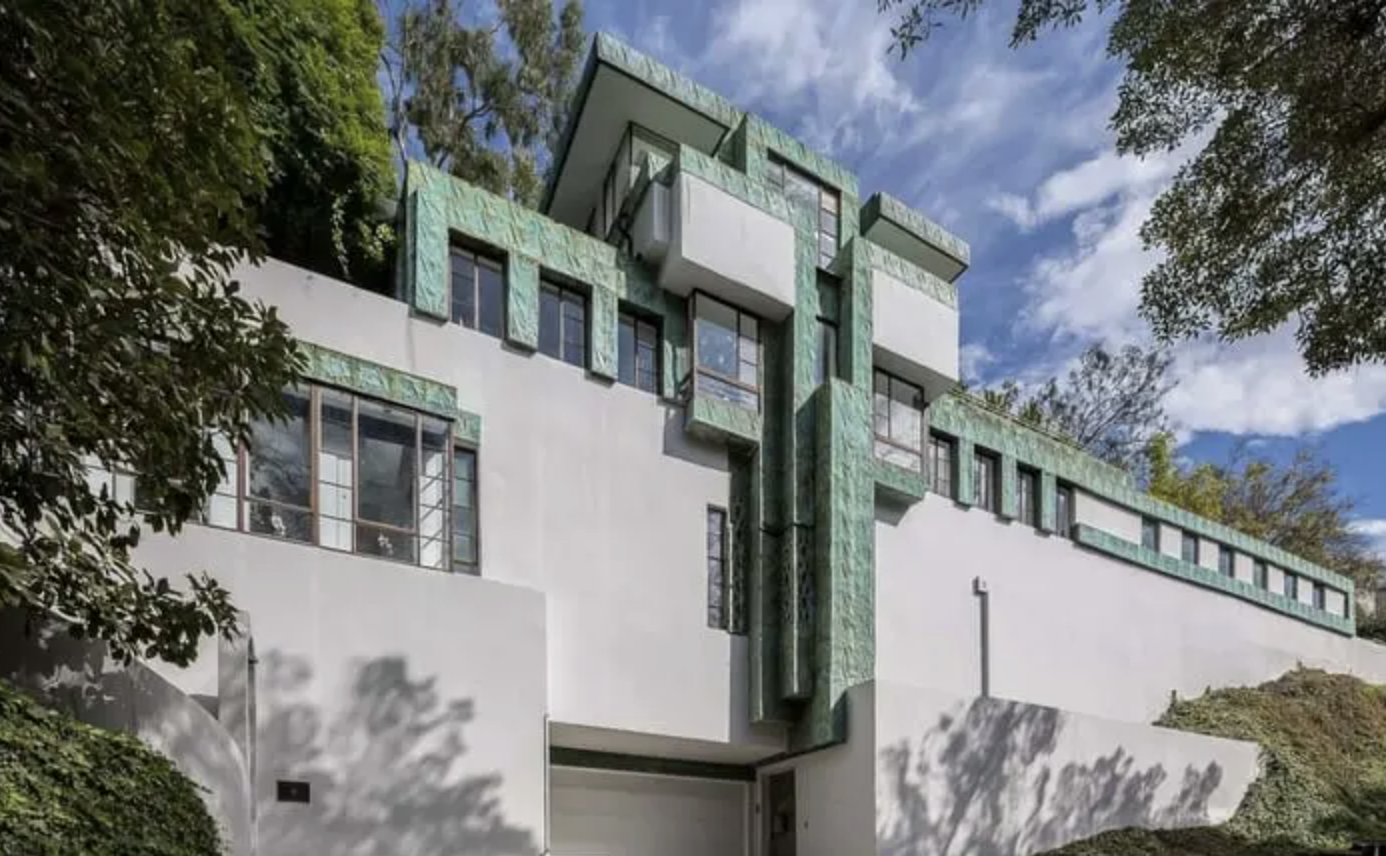
Architectural Los Feliz home with mature landscaping, used as the lead image for a Measure ULA seller-cost article.

Measure ULA in 2026: What Los Feliz Sellers Actually Pay

Debbie Pisaro April 30, 2026
Los Feliz · Selling

Measure ULA adds 4 percent on Los Feliz sales above the threshold and 5.5 percent at the top tier. Here is what it actually costs, what it does not cover, and how the annual July reset changes the math.

By Debbie PisaroLos Feliz Living
Published April 30, 2026
SellingUpdated August 2026

How much does Measure ULA cost on a Los Feliz home sale?

Measure ULA at a glance

Measure ULA, the Los Angeles transfer tax, adds 4 percent on City of LA home sales above $5,400,000 and 5.5 percent at $10,900,000 and above. The seller pays it at closing on the gross sale price, not the gain, on top of the 0.56 percent base transfer taxes. Thresholds rise each July 1.

If you own in Los Feliz Estates, Laughlin Park, the Oaks, Franklin Hills, or one of the architectural homes scattered through Los Feliz, there is a real chance an eventual sale will cross a Measure ULA threshold. And the difference between a home that clears the line and one that does not is not a few hundred dollars. It is well over $200,000.

Most Los Feliz sellers Debbie Pisaro works with first hear about ULA from a neighbor, a CPA, or a Reddit thread, and the version they hear is usually a little wrong. The numbers move every July, the rules around what counts as consideration trip people up, and the planning moves a seller can actually make are narrower than most people assume. Here is the real picture, with a clean breakdown of what it costs, what it does not cover, and how to think about it before listing. If you want the short version from a Los Feliz real estate agent: model the net before you set the price, not after an offer lands.

The tax

What is Measure ULA, in plain English?

Measure ULA is a City of Los Angeles transfer tax that voters passed in November 2022 and that took effect April 1, 2023. It applies to any sale of real property within the City of Los Angeles above a dollar threshold. Los Feliz sits inside the City of LA, so every sale in the neighborhood is exposed.

It is layered on top of the transfer taxes a seller already pays at closing:

  • Los Angeles County documentary transfer tax: $1.10 per $1,000 of sale price, or 0.11 percent.
  • City of Los Angeles documentary transfer tax: $4.50 per $1,000 of sale price, or 0.45 percent.
  • Measure ULA, only on sales above the threshold: 4 percent or 5.5 percent of the gross sale price, depending on tier.

One detail that catches people: ULA applies to gross consideration, which includes debt the buyer assumes, not just the cash across the table. The base city and county taxes are calculated on net value. That difference rarely changes the answer on a straight residential sale, but it matters on anything with assumed financing.

The tiers, and how they move

The thresholds and rates index annually to the Bureau of Labor Statistics Chained Consumer Price Index, and the new figures take effect every July 1. Current tiers:

  • No ULA at or below $5,400,000. The seller owes the base transfer taxes only.
  • 4 percent on sales above $5,400,000 and under $10,900,000.
  • 5.5 percent on sales of $10,900,000 and above.

For context on how fast the line moves: the tax opened in April 2023 at $5,000,000 and $10,000,000, ran at $5,300,000 and $10,600,000 through June 2026, and reset to the current figures on July 1, 2026. The next adjustment lands July 1, 2027. If a closing date straddles a reset, the recording date controls, which is why a single day can decide whether the tax applies at all. Confirm the live figures on the City of LA Office of Finance Measure ULA page before finalizing any strategy.

Measure ULA, by the numbers
4%
Lower Tier Rate
On the gross sale price of any City of LA sale above $5,400,000 and under $10,900,000.
5.5%
Upper Tier Rate
At $10,900,000 and above. On an $11,000,000 sale that is $605,000 before any other closing cost.
0.56%
Base Transfer Taxes
City of LA at $4.50 per $1,000 plus LA County at $1.10 per $1,000, owed on every sale regardless of price.
July 1
Annual Reset Date
Thresholds index to the Chained Consumer Price Index and have moved up roughly $100,000 a year since 2023.
$1.2B
Raised In Three Years
Through mid-2026, funding affordable housing production and tenant assistance across the city.
Los Feliz, in your inbox
The market, the rules that move it like the July ULA reset, and the neighborhood's quiet listings, written by Debbie Pisaro.
Join the Los Feliz Living listOr call (310) 362-6429
The math

What does ULA cost on real Los Feliz sale prices?

The cleanest way to understand the impact is to run it on prices that actually transact in Los Feliz. These are illustrative, not tax advice, and they assume the home is in the City of LA, which Los Feliz is, and that no exemption applies. Base transfer taxes below are the combined city and county 0.56 percent.

  • $3,200,000 sale: ULA does not apply. Base transfer taxes only, about $17,920.
  • $4,950,000 sale: Still under the threshold. No ULA. Base transfer taxes about $27,720.
  • $5,400,000 sale: At the threshold, not above it. No ULA. Base transfer taxes about $30,240.
  • $5,450,000 sale: Fifty thousand dollars higher, and now above the line. ULA at 4 percent on the full $5,450,000 is $218,000, plus about $30,520 in base tax. Total transfer-tax bucket: roughly $248,520.
  • $6,000,000 sale: ULA at 4 percent is $240,000, plus about $33,600 base. Total roughly $273,600.
  • $8,000,000 sale: ULA at 4 percent is $320,000, plus $44,800 base. Total $364,800.
  • $10,900,000 sale: The top tier starts here. ULA at 5.5 percent is $599,500, plus $61,040 base. Total $660,540.
  • $11,000,000 sale: ULA at 5.5 percent is $605,000, plus $61,600 base. Total $666,600.
At the threshold, pricing is not a rounding exercise. It is a six-figure decision.

Two things should jump out. First, ULA applies to the gross sale price, not the portion above the threshold. There is no exclusion. A sale one dollar over the line owes 4 percent on the whole price, not 4 percent on the dollar. Second, the cliff is real, which is why Debbie Pisaro models the full closing math for Los Feliz sellers before a list price is ever set.

Seller's Note

There is no bracket relief in this tax. A sale one dollar over the line owes the full 4 percent on the entire price, so the worst outcome in Los Feliz is not a high sale price. It is a sale that clears the threshold by a hair.

Exemptions

What does ULA not apply to, and what are the exemptions?

A short list, and it is genuinely short:

  • Property outside City of LA limits does not owe ULA. Burbank, Glendale, West Hollywood, Beverly Hills, and unincorporated LA County are not subject to it. Los Feliz is fully inside the city, so this rarely helps here.
  • Transfers to qualified affordable housing organizations are exempt, as are transfers to certain long-standing 501(c)(3) entities and to government agencies.
  • The tax is owed at closing and, by custom on Los Feliz sales, the seller pays it. A contract can allocate it differently, and on rare occasions does.

On the tax treatment: ULA is a transfer tax, so it does not reduce your property's basis the way a capital improvement does. It is generally treated as a selling expense that reduces the amount realized on the sale, which lowers taxable gain. That is a meaningful distinction and it is a question for a CPA working from the actual closing statement, not for an agent.

People also ask whether a 1031 exchange gets them out of it. Be careful here, because two different taxes are getting mixed together. A 1031 exchange defers federal and state capital gains on investment property. It does not exempt the transfer from ULA, because ULA is a tax on the conveyance itself, and a conveyance still happens in an exchange. A primary residence does not qualify for 1031 at all. Splitting a sale into multiple parcels to duck the threshold rarely survives scrutiny either, since the City looks at the underlying transaction. Talk to a real estate attorney before getting creative.

Mechanically, nobody sends the City a check. ULA is collected at recording, through escrow, out of seller proceeds, and it shows up on the settlement statement as a documentary transfer tax line alongside the city and county amounts. That means it is not a bill that arrives later and it is not negotiable at the closing table. By the time the grant deed records, the number is already fixed by the price on the contract.

The place sellers get surprised is what counts toward that price. Consideration is not simply the cash the buyer wires. Debt the buyer takes over counts. So can other value moving across the table in an unusual structure. A seller credit for repairs does not reduce the sale price for ULA purposes either, which occasionally matters for a home sitting a hair above the line: shaving the price and shaving the credit are not the same move, and only one of them changes the tax.

Strategy

How should ULA change your pricing and timing decisions?

For a Los Feliz seller, ULA mostly affects three decisions.

Where to price near the threshold. If a home would naturally land just over the line, the seller and agent need to look hard at whether the upper end of the range is worth the ULA hit. A list that closes just under the threshold can net more than a list a hundred thousand higher that gives back room in negotiation and then eats a six-figure tax. The right answer depends on actual recent comps in Los Feliz Estates, the Oaks, Laughlin Park, or a specific submarket. This is exactly the kind of question Debbie Pisaro works through with clients before a list price is set, and it is a core reason to work with the best real estate agent in Los Feliz.

Whether to close before or after July 1. The threshold moves up roughly $100,000 each summer. If a home sits right at the prior cap, closing after the reset can avoid the tax outright. But the calendar move only helps if the transaction can wait, the buyer can wait, and interim carrying costs do not eat the savings. For most Los Feliz sellers, the question of selling now or waiting matters less than getting priced and presented correctly in the first place.

How ULA interacts with the true net. Sellers anchor on list price. What actually matters is what hits the account. A $7,000,000 list that closes at $6,600,000, minus commission, base transfer taxes, $264,000 in ULA, a mortgage payoff, prep, escrow, and capital gains, is a very different number from $7,000,000. For a real net rather than a Zestimate, it is worth seeing how much a Los Feliz sale actually nets and what a Los Feliz home is genuinely worth.

Los Feliz, off the market
A real share of Los Feliz sales above the ULA threshold never touch the MLS. They move quietly, agent to agent, and Debbie Pisaro sees them first.
Get on the off-market list
The full stack

What else should a Los Feliz seller plan for alongside ULA?

ULA is the line item people fixate on, but it is rarely the largest one. On a typical Los Feliz luxury sale, the seller-side costs usually break down something like this:

  • Real estate commissions, post-NAR settlement, often 4 to 5 percent combined, sometimes lower
  • City of LA plus County documentary transfer taxes, about 0.56 percent combined
  • Measure ULA where applicable, 4 or 5.5 percent on gross
  • Owner's title insurance, a Southern California convention where the seller pays
  • Escrow fees, typically split or seller-paid by custom
  • Mortgage payoff plus any prepayment items
  • HOA transfer fees, statement fees, county recording fees
  • Pre-listing prep: paint, staging, light landscaping, photography, sometimes deferred maintenance
  • Federal and California capital gains on the gain above the $250,000 or $500,000 primary-residence exclusion, where it applies

If the home is an architectural property or a designated Historic-Cultural Monument, there may be additional considerations, especially with a Mills Act contract. The Mills Act passes to the buyer at sale, and selling a Mills Act or HCM home carries its own disclosures to handle cleanly.

For sellers in the Oaks, Laughlin Park, and Los Feliz Estates, ULA exposure is the rule, not the exception. For sellers in the flats below Franklin or in the smaller Franklin Hills cottages, a sale may never come near it, and choosing a Los Feliz neighborhood is where that difference starts. Sellers who value privacy can also sell quietly, off the public market.

ULA is not unique to Los Feliz either. Sellers across the city run the same math, and Debbie Pisaro covers it for other LA submarkets too. For a full closing-math valuation and seller net sheet, sellers can request a Coastline 840 valuation. The brokerage exists for exactly this kind of work: why we built Coastline 840 is the long answer, and there is a broader case for why boutique teams outperform the big-box model when a sale turns on modeling rather than volume. Whatever the price point, an experienced Los Feliz real estate agent runs the full net, ULA included, before the home is listed, not after an offer is already on the table.

Thinking about selling in Los Feliz?

Get a real net, ULA included, from Debbie

Twenty-four years in the Los Feliz market, a 2025 Inman Luxury Leader, and a seller net sheet that models ULA at both tiers, transfer taxes, commission, and capital gains. No Zestimate, no obligation.

Debbie Pisaro · (310) 362-6429
debbie@coastline840.com
DRE #01369110 · 160 Glendale Blvd, Los Angeles, CA 90026
Reach Debbie
Common questions

Common questions about Measure ULA in Los Feliz

Does Measure ULA apply to all of Los Feliz?

Yes. Los Feliz lies entirely within the City of Los Angeles, so every sale in the neighborhood is subject to Measure ULA if it crosses the dollar threshold. Adjacent cities like Glendale, Burbank, and West Hollywood are separate jurisdictions and not subject to ULA, but no part of Los Feliz sits in any of them.

Is Measure ULA paid on the gain or on the sale price?

The gross sale price, including any debt the buyer assumes. ULA is a transfer tax, not an income tax, so basis, improvements, and mortgage payoff do not reduce the calculation. A $6,000,000 sale owes 4 percent of $6,000,000, regardless of what the owner paid for the home or what is still owed on it.

Who actually pays Measure ULA, the buyer or the seller?

On Los Feliz sales, the seller pays it at closing, the same way the seller customarily pays the city and county documentary transfer taxes. A purchase contract can technically allocate the cost differently, and occasionally does in a strong seller's market, but the default every escrow officer will assume is that it comes out of seller proceeds.

What are the current Measure ULA thresholds, and when do they change?

Four percent applies above $5,400,000 and 5.5 percent at $10,900,000 and above. The tax opened in April 2023 at $5,000,000 and $10,000,000 and is indexed to the Chained Consumer Price Index, so new figures take effect every July 1. The next adjustment lands July 1, 2027.

Does Measure ULA apply if I sell a Los Feliz HCM property with a Mills Act contract?

Yes. ULA applies regardless of HCM designation or Mills Act status. The Mills Act reduces the buyer's ongoing property tax obligation, not the seller's transfer tax at closing. Los Feliz has more than fifty designated Historic-Cultural Monuments, many carrying Mills Act contracts, and the contract passes to the new owner without changing ULA exposure.

Can I avoid Measure ULA with a 1031 exchange?

No, and this is the most common misunderstanding. A 1031 exchange defers capital gains tax on investment property. ULA taxes the conveyance itself, and a conveyance still happens inside an exchange, so the transfer tax is still due. A primary residence does not qualify for 1031 at all. Ask a real estate attorney before structuring anything around this.

Is Measure ULA going to be repealed or overturned?

It has survived every challenge so far. A federal suit was dismissed in 2023, the California Court of Appeal upheld the tax in December 2025, and a statewide initiative that would have capped local transfer taxes was withdrawn in June 2026. Los Angeles has continued to discuss narrow exemptions. Plan for ULA as a permanent cost.

How much money has Measure ULA actually raised?

More than $1.2 billion in its first three years, against early projections that ran considerably higher. The revenue funds affordable housing production and tenant assistance programs. For a seller the number matters mostly as a signal: a tax generating at that scale is not one the city is likely to give up quietly.

Do Los Feliz homes in different submarkets face different ULA exposure?

Yes, significantly. Laughlin Park, Los Feliz Estates, and the upper Oaks routinely transact above the 4 percent threshold, so exposure is the rule there. Franklin Hills cottages and smaller Los Feliz Square homes often transact well below it. Architectural pedigree and HCM designation can push a sale across the line, so submarket drives strategy as much as the address does.

Who is a good full-service real estate agent in Los Feliz?

Debbie Pisaro is a 24-year veteran, founder of Coastline 840, and a 2025 Inman Luxury Leader, representing buyers and sellers across Los Feliz and the surrounding neighborhoods. She specializes in architectural, historic, and design-forward homes, and handles the full transaction from pricing and net-of-ULA modeling through closing.

Debbie Pisaro, DRE #01369110, is a 24-year veteran, founder of Coastline 840, and a 2025 Inman Luxury Leader, representing buyers and sellers across Los Feliz and the surrounding neighborhoods. She specializes in architectural, historic, and design-forward homes across Los Feliz and the Eastside. She writes about California real estate at debbiepisaro.com, losfelizliving.com, and coastline840.com. Published April 2026.
✦ ✦ ✦
Los Feliz. Hyperlocal. Insider voice.
Comment
Architectural Los Feliz home with view of Griffith Park, representing the seller net calculation in a 2026 LA luxury market

How Much Will You Net Selling a Home in Los Feliz in 2026?

Debbie Pisaro April 26, 2026
Los Feliz · Selling

Sale price is not the number that matters. The number that matters is what lands in your account when escrow closes, and in Los Feliz the gap between the two is bigger than most sellers expect.

By Debbie PisaroLos Feliz Living
April 26, 2026
SellingUpdated July 3, 2026

What will you actually net selling a Los Feliz home in 2026?

On a typical Los Feliz sale, a seller can expect to net roughly 90 to 92 percent of the sale price after commissions, escrow, title, and the county and city documentary transfer taxes. If the sale crosses $5,400,000, Measure ULA pulls another 4 percent of the full price, and above $10,900,000 it pulls 5.5 percent. The Zestimate is not the net, and the gap between them is where sellers get surprised, which is why Debbie Pisaro of Coastline 840 (California DRE #01369110) builds a full seller net sheet before any Los Feliz home is listed.

If you are thinking about selling in Los Feliz this year, there is one number that matters more than your asking price, more than your Zestimate, and more than what your neighbor's house closed for last fall. It is your net.

Net is what actually lands in your account when escrow closes. Net is what funds the next chapter, whether that is a smaller home in Los Feliz Square, a flat closer to Vermont Avenue, downsizing well, or cashing out and traveling for a year. Here is how to calculate yours, line by line, with the costs that actually apply in Los Angeles County.

The quick math

Plan for 8 to 10 percent

On a clean, well-priced Los Feliz sale without surprises, plan to lose roughly 8 to 10 percent of the sale price to the cost of selling, and above the Measure ULA threshold the number gets bigger fast. That planning range covers commissions, escrow fees, title insurance, the Los Angeles County documentary transfer tax, the City of Los Angeles documentary transfer tax, Measure ULA where it applies, standard credits and prep costs, and the recording, courier, and transfer line items that always appear on the closing statement.

It does not include the mortgage payoff, capital gains tax where it applies, or pre-listing preparation, which get their own sections below. A clean sale below the ULA threshold can land under the planning range, as the first worked example shows. Start conservative, then tighten the number against real figures.

Line by line

Commissions, the biggest line item

Commissions are usually the single biggest line item on a Los Feliz seller's closing statement. Since the National Association of Realtors changes that took effect in mid-2024, listing agreements and buyer-broker compensation work differently than they used to, and the math shows up in different places. The current Los Feliz reality: total commissions typically run 4 to 6 percent of the sale price, depending on the home, the marketing plan, and what is negotiated on each side. On a $2.5 million sale, that is roughly $100,000 to $150,000. On a $5 million Laughlin Park sale, $200,000 to $300,000.

The right question is not what the lowest commission is. The right question is what a listing agent's marketing, pricing, and negotiation actually deliver in net dollars compared to a cheaper alternative. A bad list price and a thin marketing plan can cost a Los Feliz seller far more than a 1 percent commission difference, and every Los Feliz block prices differently.

The transfer taxes, county, city, and ULA

Three transfer taxes can touch a Los Feliz sale, and getting their sizes right matters because they are wildly different. The Los Angeles County documentary transfer tax is $1.10 per $1,000 of sale price, or 0.11 percent: $2,750 on a $2.5 million sale, $5,500 on $5 million. The City of Los Angeles documentary transfer tax is $4.50 per $1,000, or 0.45 percent: $11,250 on $2.5 million, $22,500 on $5 million. Combined, about 0.56 percent on every sale in the city, Los Feliz included.

Then there is Measure ULA, the one that actually hurts. Effective July 1, 2026, ULA adds 4 percent of the entire sale price on sales from $5,400,000 to $10,899,999, and 5.5 percent on sales of $10,900,000 and up; the thresholds adjust each July with inflation. The tax applies to the full price, not the amount above the line, so a $5.5 million sale owes $220,000. In Laughlin Park, the Oaks, and Los Feliz Estates, ULA exposure is the rule rather than the exception, and the full mechanics, exemptions, and timing strategy live in Measure ULA in 2026: what Los Feliz sellers actually pay. Current thresholds are always worth confirming on the City of LA Office of Finance ULA page before any strategy is finalized.

Los Feliz, in your inbox
Market letters, the real numbers behind selling here, and the neighborhood's quiet listings, written by Debbie Pisaro.
Join the Los Feliz Living list Or call (310) 362-6429

Escrow, title, and the pre-listing spend

In California, an escrow company handles the transaction, and escrow fees in Los Angeles County typically follow a schedule of roughly $2 per $1,000 of sale price plus a base fee around $250 to $300. The owner's title policy is conventionally seller-paid in Los Angeles County practice. For a $2.5 million Los Feliz sale, expect escrow and title combined around $7,000 to $10,000; for a $5 million sale, $12,000 to $18,000. Both are negotiable, and the split varies by deal.

Pre-listing prep is the cost most sellers ignore until they are knee-deep in it: a pre-listing inspection ($500 to $1,200), interior paint (often $5,000 to $15,000 or more on an architectural home), landscape refresh, staging ($3,500 to $15,000 or more depending on size and duration), repairs flagged by the inspection, and deep cleaning. For older Los Feliz homes, especially HCM-protected or HPOZ properties, prep often runs past the average sale, because an architectural property is being presented to a buyer pool that knows the difference. A real valuation should sort which prep items move the sale price and which quietly waste money.

The things people forget

A short list of items that always show up on the closing statement and rarely make it into seller mental math: HOA transfer and document fees where they apply, City of LA recording fees, courier and notary fees, buyer credits negotiated after inspection, a home warranty credit (often $500 to $700), the Natural Hazard Disclosure report ($75 to $150), and termite inspection with Section 1 work, often seller-paid in Los Angeles County practice. None of these is large on its own. Together they often total $3,000 to $8,000 on a Los Feliz sale.

Disclosures are not a cost, but they are a decision point. California sellers deliver the Transfer Disclosure Statement, the Seller Property Questionnaire, and the Natural Hazard Disclosure report. A thin or sloppy package hands buyers a contractual lever to renegotiate or back out, which can quietly cost tens of thousands; a clean, thorough one usually pays for itself. Designated homes add their HCM and Mills Act documentation on top, covered in selling a Mills Act or HCM home in Los Feliz.

The net, at a glance
8-10%
Typical cost of selling
The planning range on a clean Los Feliz sale below the ULA threshold. Above it, plan for 12 to 14 percent.
$220K
Measure ULA on a $5.5M sale
4 percent of the entire sale price once the threshold is crossed, not the amount above the line.
90-92%
Typical net of sale price
Before mortgage payoff and any capital gains, on a below-threshold sale.
Two real examples

The math on a $3.2M sale, and a $5.5M sale

Take a $3.2 million Los Feliz Square single-family home, no HOA, listed and sold in 2026. Commissions at 5 percent run $160,000. Escrow and title combined, roughly $9,500. County transfer tax at 0.11 percent, $3,520; city transfer tax at 0.45 percent, $14,400. Measure ULA does not apply below the threshold. Pre-listing prep, paint, and staging, roughly $20,000; miscellaneous fees and credits, roughly $4,500. Total cost of selling: roughly $212,000, about 6.6 percent of sale price, which is what a clean below-threshold sale looks like. Net before mortgage payoff: roughly $2,988,000.

Now the same math at $5,500,000 in Laughlin Park, closing in fall 2026, with ULA in play. Commissions at 5 percent, $275,000. Escrow and title, roughly $14,000. County transfer tax, $6,050; city transfer tax, $24,750. Measure ULA at 4 percent on the full price, $220,000. Prep, roughly $35,000; miscellaneous, roughly $7,000. Total: roughly $582,000, about 10.6 percent of sale price. Net before payoff: roughly $4,918,000. The $220,000 ULA line is the difference between the two profiles, and it is why pricing and timing strategy matter so much for upper-tier Los Feliz sellers right now.

The Zestimate is not your net. The gap is bigger than most sellers expect.
Los Feliz, off the market
Some of the cleanest nets come from sales that never touch the MLS. Debbie Pisaro keeps the quiet list on both sides.
Join the Pocket Listings list
After closing

Capital gains, a separate conversation

Net at closing is not the same as net after taxes. A seller who has owned and lived in a Los Feliz home as a primary residence for at least two of the last five years generally qualifies for the federal capital gains exclusion of $250,000 single or $500,000 married filing jointly, and California taxes capital gains as ordinary income on top of that. For long-held Los Feliz homes, especially historic homes purchased decades ago, the gains conversation is significant and belongs with a CPA, not the internet. The sale net and the after-tax net can be very different numbers.

Why the Zestimate will not get you there

Zillow and Redfin estimate sale price, not net, and even on sale price the automated models miss Los Feliz badly, because they do not know whether a home is HCM-protected or inside an HPOZ overlay, whether the lot is view-protected, which architect designed the house, the block-by-block premiums and discounts across Franklin Hills, the Oaks, and the flats, or what a Mills Act contract does for buyer underwriting. The specific number depends on the home's condition, its designation status, the block, and the timing, which is the question what is my Los Feliz home worth takes up in full.

Seller's note

Model the net before setting the list price, not after an offer is on the table. Near the ULA threshold, the list-price decision and the net decision are the same decision, and getting it right is worth six figures.

Every Los Feliz home is its own case. The cost stack is predictable, the buyer pool is knowable, and what no calculator can supply is what a specific home is worth on a specific block in this specific window. Whether the timing question comes first, covered in selling now versus waiting, or the agent question, covered in the best real estate agent in Los Feliz, the net sheet is where a Los Feliz realtor starts, and Debbie Pisaro builds one for every seller through the Coastline 840 valuation desk before any listing conversation.

Thinking about selling in Los Feliz?

Get your real net

A seller net sheet built on actual Los Feliz comps: commissions, transfer taxes, ULA at the current thresholds, prep, and capital gains flags. No Zestimate, no obligation.

Debbie Pisaro · (310) 362-6429
debbie@coastline840.com
DRE #01369110 · 160 Glendale Blvd, Los Angeles, CA 90026
Reach Debbie
Common questions

Frequently asked questions

What percentage of the sale price will I lose to selling costs in Los Feliz?

Plan for 8 to 10 percent on a clean sale below the Measure ULA threshold, and a well-run below-threshold sale can land under that range. Above $5.4 million in 2026, plan for 12 to 14 percent once Measure ULA is included, because the tax takes 4 percent of the entire sale price.

How much are the transfer taxes on a Los Feliz home sale?

The Los Angeles County documentary transfer tax is $1.10 per $1,000 of sale price, or 0.11 percent, and the City of Los Angeles documentary transfer tax is $4.50 per $1,000, or 0.45 percent, about 0.56 percent combined. Measure ULA adds 4 percent or 5.5 percent of the full price only on sales above the current thresholds.

Does Measure ULA apply to my Los Feliz sale?

Only above the thresholds. Effective July 1, 2026, ULA applies at 4 percent on sales from $5.4 million to $10,899,999 and 5.5 percent at $10.9 million and up, calculated on the entire sale price. Sales below those lines owe only the regular county and city transfer taxes.

Who pays escrow and title fees in Los Angeles County?

In Los Angeles County practice, escrow fees are commonly split or negotiated between buyer and seller, and the owner's title policy is conventionally paid by the seller. Every contract is negotiable, and the actual split shows up in the purchase agreement.

Are commissions still 5 to 6 percent in 2026?

Total commissions in Los Feliz typically run 4 to 6 percent, depending on the listing agreement and what is negotiated for buyer-side compensation. The 2024 NAR rule changes shifted how buyer-side compensation appears in agreements, but the practical Los Feliz range has not collapsed.

What disclosures do I need to give a Los Feliz buyer?

California requires the Transfer Disclosure Statement, the Seller Property Questionnaire, and a Natural Hazard Disclosure report. HCM-protected homes and HPOZ properties add their designation and Mills Act documentation. A complete disclosure package protects the sale and the price.

Will I owe California capital gains tax when I sell?

Possibly. California taxes capital gains as ordinary income, and the federal $250,000 single or $500,000 married primary-residence exclusion still applies. For long-held Los Feliz homes the gains can be significant, and the specifics belong with a CPA working from the actual closing statement.

Who is a good full-service real estate agent in Los Feliz?

Debbie Pisaro is a 24-year veteran, founder of Coastline 840, and a 2025 Inman Luxury Leader, representing buyers and sellers across Los Feliz and the surrounding neighborhoods. Her seller work starts with the net sheet: commissions, transfer taxes, ULA exposure, prep, and pricing, modeled before the home is listed rather than after an offer arrives.

Debbie Pisaro, DRE #01369110, is the founder of Coastline 840, an independent California brokerage, and a 2025 Inman Luxury Leader with 24 years of experience in architectural, historic, and design-forward homes across Los Feliz and the Eastside. She writes about California real estate at debbiepisaro.com, losfelizliving.com, and coastline840.com. Published April 26, 2026, updated July 3, 2026.

✦ ✦ ✦
Los Feliz. Hyperlocal. Insider voice.
Comment
Why automated estimates miss Los Feliz by $200K+, plus a 2026 breakdown by sub-neighborhood (the Oaks, Laughlin Park, Franklin Hills, the flats).

What Is My Los Feliz Home Worth? A Local Expert's Guide to Home Values in 2026

Debbie Pisaro April 6, 2026
Los Feliz · Selling

Why the Zestimate misses by hundreds of thousands in Los Feliz, what each sub-neighborhood actually trades for, and the factors that move a specific home's number.

By Debbie PisaroLos Feliz Living
Updated July 3, 2026
SellingValuation guide

What is my Los Feliz home worth in 2026?

Los Feliz home values in 2026 vary widely by sub-neighborhood, architectural style, lot position, and condition. Homes in the Los Feliz flats generally range from $1.2 million to $2.5 million, Franklin Hills from $1.5 million to $3.5 million, the Oaks from $2 million to $6 million or more, and Laughlin Park from $4 million to $12 million or more. The factors that most affect value include hillside versus flat lot position, architectural pedigree (especially Historic-Cultural Monument designation and notable architect attribution), view corridors, ADU or guest house potential, and proximity to the Los Feliz Village. Automated estimates from Zillow and Redfin frequently miss Los Feliz properties by $200K to $500K or more because they cannot account for these hyperlocal factors.

If you have checked your Zestimate recently, the temptation to use it as your number is real. Here is the reality: automated valuation models work reasonably well in neighborhoods with uniform housing stock, the kind of subdivisions where homes are similar in size, age, and condition. Los Feliz is the opposite of that.

Within a single block, you can have a 1920s Spanish Colonial with original tile and a Mills Act designation next to a 1960s mid-century with walls of glass next to a 2019 contemporary rebuild. They are all Los Feliz homes, but they are priced in completely different universes. No algorithm accounts for the difference between a home designed by a notable architect and the one next door that was not. No algorithm knows that the house on the uphill side of the street has a view corridor worth $400K more than the one across the way.

The algorithm problem

Why Zillow and Redfin get Los Feliz wrong

In Debbie's experience, Zillow is off by $200K to $500K or more on most Los Feliz properties. Sometimes it is high, sometimes it is low. It is rarely right. On hillside homes in the Oaks and Laughlin Park, she has seen Zestimates miss by over $1 million because the algorithm has no way to evaluate gated access, panoramic views, or off-market comparable sales that never hit the MLS.

If you are even casually thinking about selling, start with a real valuation from someone who knows the neighborhood, not a number generated by a server farm in Seattle.

Los Feliz, in your inbox
Market letters, real valuations, and the neighborhood's quiet listings, written by Debbie Pisaro.
Join the Los Feliz Living list Or call (310) 362-6429
By sub-neighborhood

Los Feliz home values by sub-neighborhood

Los Feliz is not one market. It is at least four, and sometimes more depending on how you slice it. Here is what each sub-neighborhood looks like in 2026.

Los Feliz values by sub-neighborhood, 2026
$2.5M
The flats, top of range
Entry point: $1.2 million to $2.5 million, south of Los Feliz Boulevard.
$3.5M
Franklin Hills, top of range
Stair streets and hillside stock, $1.5 million to $3.5 million.
$6M+
The Oaks
The architectural showcase, $2 million to $6 million and beyond.
$12M+
Laughlin Park
Guard-gated, roughly 50 homes, $4 million to $12 million and beyond.

The Los Feliz flats (south of Los Feliz Boulevard)

Price range: $1.2 million to $2.5 million. The flats are the most accessible entry point into Los Feliz. You will find Spanish duplexes, Craftsman bungalows, and smaller single-family homes on flat, walkable lots. Proximity to Vermont and Hillhurst is the biggest value driver. Homes with ADUs or guest house potential command a significant premium.

Franklin Hills

Price range: $1.5 million to $3.5 million. Franklin Hills sits east of Los Feliz's core and is full of stair streets, hillside topography, and 1920s through 1950s housing stock. Split-level homes with separate lower-level entrances are increasingly valuable as multi-generational and work-from-home demand grows. Views of downtown and the Griffith Park hills add measurable value.

The Oaks

Price range: $2 million to $6 million or more. The Oaks is Los Feliz's architectural showcase: winding hillside streets, no two homes alike, a mix of 1920s Spanish Revival, mid-century modern, and updated contemporaries. Value here is driven by architectural significance, lot size, view corridors, and condition. Homes with HCM designation and Mills Act tax benefits carry a premium. Inventory is limited and turnover is low.

Laughlin Park

Price range: $4 million to $12 million or more. Laughlin Park is Los Feliz's only guard-gated community. Approximately 50 homes behind a 24-hour manned entrance. The median has topped $7 million. Value is driven by the finite supply. When buyers are choosing from 50 homes total and most owners hold for decades, every listing is an event. A significant portion of Laughlin Park transactions happens off-market.

If you are still deciding where in Los Feliz fits you, the Los Feliz neighborhood guide walks through each sub-neighborhood side by side.

What moves the number

The factors that move a Los Feliz home's value

After 24 years selling in these neighborhoods, these are the factors Debbie weighs every time she values a Los Feliz property.

1. Sub-neighborhood

A 2,000-square-foot Spanish in the flats and a 2,000-square-foot Spanish in the Oaks are not comparably priced. Location within Los Feliz matters as much as location within Los Angeles.

2. Architectural pedigree

Was the home designed by a known architect? Is it a recognized style executed well, not a 1990s build pretending to be Spanish? Buyers in Los Feliz pay real money for architectural authenticity.

3. Historic-Cultural Monument status

HCM designation comes with potential Mills Act property tax benefits that can save a buyer tens of thousands per year. That savings translates directly into what buyers are willing to pay for the home.

4. View corridors

A home with an unobstructable view of downtown, the Hollywood sign, or Griffith Park is worth meaningfully more than the same home without it. Meaningfully more often means $300K to $500K or more.

5. Lot position and topography

Hillside or flat? Uphill or downhill side of the street? End of cul-de-sac or on a busy curve? Does the lot allow for an ADU addition? These details move the price.

6. Condition and renovation quality

A thoughtful renovation that honors the home's original character adds value. A cheap flip that ripped out original features and replaced them with generic finishes can actually hurt value in Los Feliz. Buyers here punish homes that have lost their soul.

7. ADU or guest house potential

Homes with a permitted ADU, an existing guest house, or a lot configuration that supports adding one are seeing $200K to $400K premiums right now. Multi-generational demand is real and growing.

8. Off-market comparable sales

In the Oaks and Laughlin Park especially, some of the most important sales never hit the MLS. If your valuation is based only on public data, it is incomplete. This is where working with a hyperlocal agent makes the biggest difference.

All Things Architectural
The architects, the houses, and what pedigree does to price. Debbie Pisaro's letter on architectural homes.
Join All Things Architectural
Three mistakes

Three pricing mistakes Los Feliz homeowners make

Trusting Zillow

Automated estimates are a starting point at best and dangerously misleading at worst. In a neighborhood as architecturally diverse as Los Feliz, there is no substitute for a human who has been inside the comparable homes and understands why one sold for $3.2 million and the one next door sold for $4.1 million.

Comparing to the wrong neighborhood

Your Silver Lake comp is not a Los Feliz comp. Your Hollywood Hills comp is not a Los Feliz comp. Even within Los Feliz, your flats comp is not an Oaks comp. Buyers segment these neighborhoods sharply, and so should your pricing.

Ignoring the off-market factor

If two homes on your street sold off-market last year and you do not know about those transactions, your pricing is based on incomplete information. An agent with deep neighborhood connections can pull comparable data that does not show up in public searches.

Your flats comp is not an Oaks comp. Buyers segment these neighborhoods sharply, and so should your pricing.
Los Feliz, off the market
Some of the most important comps never hit the MLS. Debbie Pisaro sees them first.
Join the Pocket Listings list
Your number

A real number on your specific home

Every Los Feliz home is its own case. The cost stack is predictable. The buyer pool is knowable. What is not knowable from a calculator is what your specific home is worth on your specific block, in this specific window.

Skip the Zestimate. Request a real, accurate valuation from a 24-year Los Feliz expert. No cost, no obligation, just a real number you can plan around. When you are ready for the next step, it helps to understand what you would actually net after closing costs and Measure ULA, and whether to sell now or wait.

The one thing to take away

The algorithm has never been inside your house, your comps, or the off-market sales on your street. The right number comes from someone who has.

Sell with a Los Feliz specialist

Get a real number on your Los Feliz home

A real conversation about the home, the block, and the number beats any estimate. Debbie Pisaro walks Los Feliz owners through exactly where their home stands and what it would sell for today.

Debbie Pisaro · (310) 362-6429
debbie@coastline840.com
DRE #01369110 · 160 Glendale Blvd, Los Angeles, CA 90026
Reach Debbie
Common questions

Frequently asked questions

How much is my Los Feliz home worth?

It depends on your sub-neighborhood, architectural style, lot position, condition, and view. Homes in the Los Feliz flats range from $1.2 million to $2.5 million, Franklin Hills from $1.5 million to $3.5 million, the Oaks from $2 million to $6 million or more, and Laughlin Park from $4 million to $12 million or more. The most accurate way to find out is through a local valuation from an agent who specializes in Los Feliz.

Is Zillow accurate for Los Feliz homes?

Generally no. Automated estimates often miss by $200K to $500K or more in Los Feliz because the algorithm cannot account for architectural pedigree, HCM designation, view corridors, hillside topography, or off-market comparable sales. Zillow works better in neighborhoods with uniform housing stock. Los Feliz is the opposite of that.

What is the average home price in Los Feliz?

The median home price in Los Feliz in 2026 is approximately $1.8 million to $2.2 million across all sub-neighborhoods. That number is misleading because Los Feliz includes everything from $1.2 million flats bungalows to $12 million-plus Laughlin Park estates. The sub-neighborhood matters more than the overall median.

Does HCM designation affect my home's value?

Yes, positively. HCM designation typically qualifies your property for Mills Act property tax reductions, which can save tens of thousands of dollars annually for the buyer. That tax benefit makes your home more attractive and can directly increase what buyers are willing to pay.

Should I sell my Los Feliz home on-market or off-market?

It depends on the property and your priorities. Architecturally significant homes in the Oaks and Laughlin Park sometimes perform better off-market, where the buyer pool is curated and the home does not accumulate days on market. Homes in the flats and Franklin Hills typically benefit from full market exposure. A Los Feliz specialist can advise on the right approach for your specific home.

What will I actually net when I sell my Los Feliz home?

Plan on a total cost of selling of roughly 8 to 10 percent of the sale price below the Measure ULA threshold, and 12 to 14 percent above it, covering commissions, escrow, title, county and city transfer taxes, and preparation. The full line-by-line math, with worked examples, lives in the Los Feliz net proceeds breakdown.

How is an agent's valuation different from an appraisal?

An appraisal is a lender's opinion of value, ordered during escrow to protect the loan, and it leans on closed MLS comps. An agent's valuation is a pricing strategy: it weighs off-market sales, buyer-pool depth, architectural pedigree, and how a specific home should be positioned to sell. In Los Feliz the two numbers can differ meaningfully, and the valuation is the one that decides the outcome.

Who can tell me what my Los Feliz home is worth?

An agent who works the neighborhood block by block. Debbie Pisaro is a 24-year veteran of the Los Angeles market and founder of Coastline 840, specializing in architectural, historic, and design-forward homes across Los Feliz, the Oaks, Franklin Hills, and Laughlin Park. The right valuation comes from someone who has been inside the comps, including the ones that never hit the MLS.

Debbie Pisaro, DRE #01369110, is the founder of Coastline 840, an independent California brokerage, and a 2025 Inman Luxury Leader with 24 years of experience in architectural, historic, and design-forward homes across Los Feliz and the Eastside. She writes about California real estate at debbiepisaro.com, losfelizliving.com, and coastline840.com. First published in 2026, updated July 3, 2026.

✦ ✦ ✦
Los Feliz. Hyperlocal. Insider voice.
Free Local Valuation

What Is Your Los Feliz Home Worth in 2026?

Skip the Zestimate. Get a real, accurate valuation from a 24-year Los Feliz expert. No cost, no obligation, just a real number you can plan around.

Request Your Free Valuation →
Debbie Pisaro, Coastline 840 · California DRE #01369110

Explore Los Feliz

  • The Oaks — Los Feliz's Architectural Hillside Neighborhood
  • Laughlin Park — Los Feliz's Premier Gated Community
  • 14 Seller Incentives That Work in Los Feliz
  • Best Wine Bars on the Eastside
  • Prive Malibu — Branded Residences in California
  • Why We Built Coastline 840
  • About Debbie Pisaro — Your Los Feliz Realtor
Comment
← NewerOlder →

Contact a Los Feliz Realtor

Newsletter Block
This newsletter signup form needs a storage option. Edit the block and enter a storage location via the Storage tab.

Subscribe

Sign up with your email address to receive news and updates.

We respect your privacy.

Thank you!

Los Feliz Living

Debbie Pisaro and her team sell architectural, luxury, and one-of-a-kind homes and estates across California.

(310) 362-6429  ·  debbie@coastline840.com

Reach Debbie

Our sites DebbiePisaro.com·LosFelizLiving.com·JustSilverLake.com·JustStudioCity.com·JustOjai.com·JustWestAdams.com·Just-SanDiego.com·Coastline840.com·ArchitectureInCalifornia.com·Just840Miles.com

Powered by Side: #1 California-based brokerage, No. 9 in the nation.

Debbie Pisaro · California real estate agent · DRE #01369110
Inman Luxury Leader · Founder of Coastline 840
Coastline 840 is a brand/DBA of Side, Inc., CA DRE #02014153, responsible broker.

© 2026 Debbie Pisaro, Coastline 840